United Arab Emirates · Managed KYC services

KYC files holding up decisions?
We clear your UAE backlog.

We complete onboarding, CDD remediation and periodic reviews for UAE financial services firms. Qualified compliance reviewers check the work under your AML policy and return documented files for your team’s decision.

Dubai and DIFC · Abu Dhabi and ADGM · Your team keeps approval

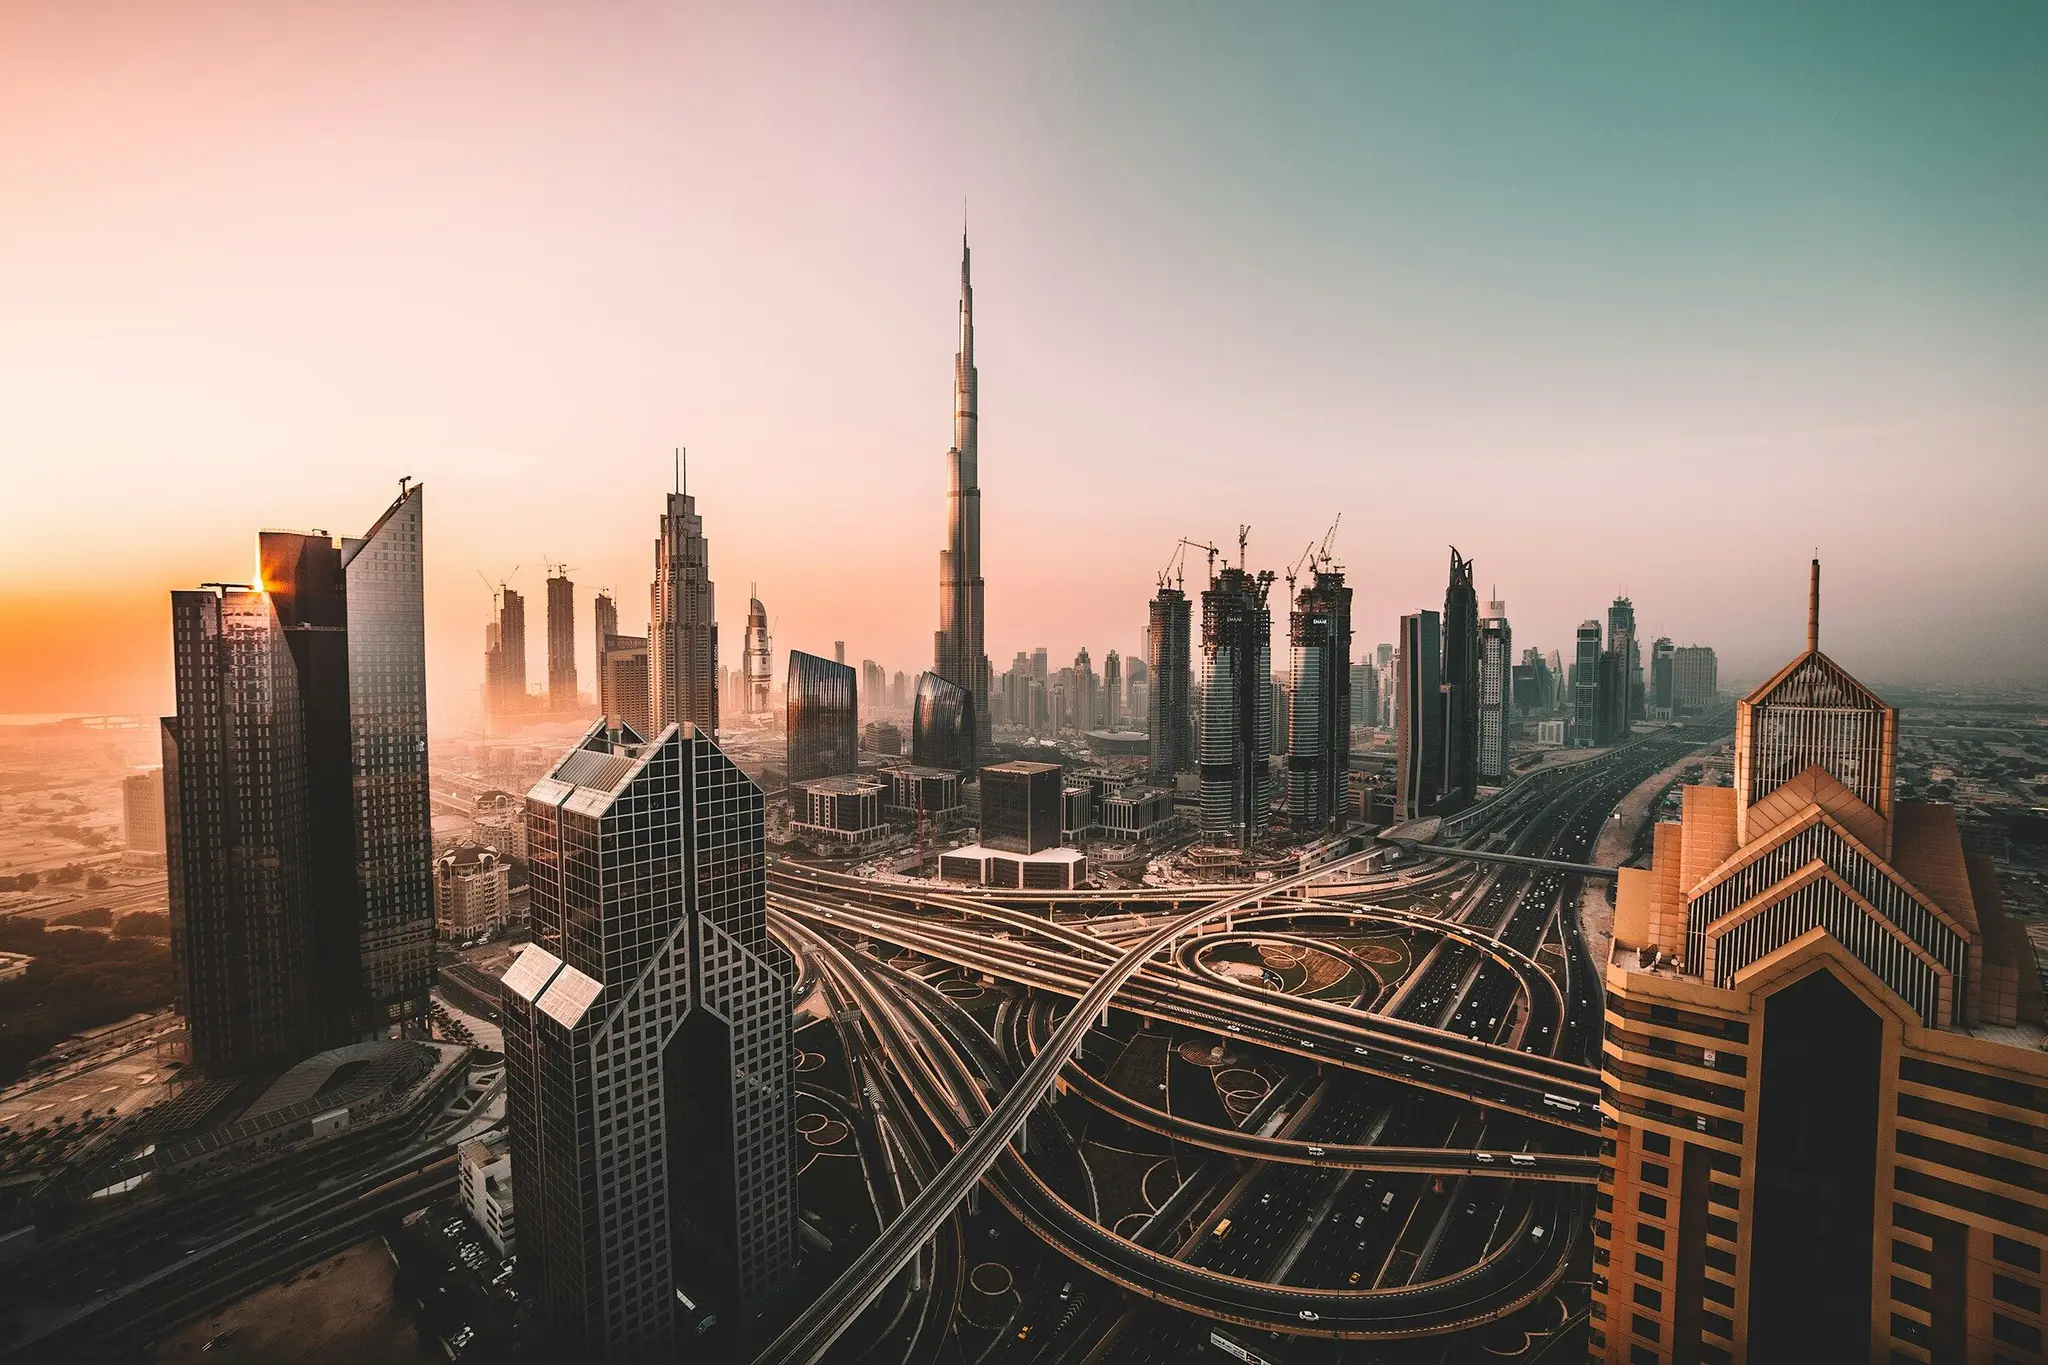
Burj Khalifa and the Downtown Dubai skyline at sunrise, United Arab Emirates

KYC outsourcing and CDD remediation

Put a scope and a date on the backlog.

Engage us for a remediation project or recurring customer reviews. We agree the case population, evidence requirements and escalation routes before starting.

01 · Customer onboarding

Get the evidence ready for approval.

We review identity documents, trace ownership and control, and screen the relevant parties. Your approver receives the proposed risk assessment, supporting evidence and unresolved questions under your AML policy.

02 · KYC remediation

Close the gaps keeping files open.

An ownership chain ends at an offshore holding company. A source-of-funds explanation lacks evidence. We work the agreed population, document the gaps and track remediation. Missing evidence stays visible at handover.

03 · Periodic reviews

Work through overdue customer reviews.

We refresh CDD and screening, document changes in ownership or activity, and reassess risk under your methodology. Recurring reviews follow your approved schedule, with trigger-event work scoped separately when needed.

Who we support in the UAE

The file follows the customer relationship.

A fund investor, a trading-account holder and a wealth-management client need different checks. We scope the review around the service your entity provides.

Funds and administrators

Investor onboarding, subscription-related CDD and periodic reviews. We define the investor or intermediary relationship and distinguish the fund’s obligations from the manager’s or administrator’s own responsibilities.

Banks and brokerages

Individual and corporate customer reviews, including ownership, authorised signatories and expected activity. We agree the applicable supervisor and evidence standard before reviewing a population.

Asset and wealth managers

Client onboarding and reviews of corporate, family and trust structures. We document control, relevant parties and source-of-funds or source-of-wealth evidence where required, with higher-risk findings escalated.

UAE AML compliance · CBUAE · DFSA · FSRA

Agree the rules before the first file.

Federal AML legislation applies alongside your supervisor’s requirements. DIFC firms must consider DFSA rules; ADGM firms must consider FSRA rules. Central Bank-supervised institutions have their own applicable standards.

We identify the entity and review scope with your team, then work under its approved policy. Your firm oversees the engagement and retains its compliance responsibilities.

Read the UAE guide

The federal framework now includes Federal Decree-Law No. 10 of 2025 and Cabinet Resolution No. 134 of 2025. Our UAE AML guide explains CDD, beneficial ownership, sanctions, goAML and the distinction between outsourcing and reliance.

What you receive

A file your approver can follow.

Each case connects the evidence to the reviewer’s conclusions. Missing documents and unresolved risk questions stay visible.

Included in the file

Identity and ownership evidence

Indexed customer documents, an ownership and control assessment, and evidence for the relevant beneficial owners and authorised representatives.

Included in the file

Screening rationale

Sanctions, PEP and adverse-media results with the identifiers checked, reviewed-match conclusions and unresolved concerns for escalation.

Included in the file

Risk assessment and open questions

The proposed risk rating under your methodology, supporting source-of-funds and wealth work where required, and a clear record of missing evidence.

Included in the file

Human review and handover record

Reviewer conclusions, an exception log and an audit trail for your authorised approver. Your team can follow what was checked and what still needs a decision.

The process

Start with your regulator, case count and deadline.

  1. 01 · Scope

    Define the population.

    Share the entity type, regulator, number of files and target date. We agree the policy, deliverables, access and price before customer documents change hands.

  2. 02 · Work & review

    We work each case.

    Agents organise documents and prepare the first pass. Qualified compliance reviewers test the evidence and reasoning, then escalate unresolved or higher-risk cases.

  3. 03 · Handover

    Your team decides.

    Receive reviewed files and an exception log. Your authorised team keeps acceptance, high-risk approvals and reporting decisions. We agree any recurring review cycle with you.

If an administrator already performs your KYC, Shadow KYC file testing can be scoped separately to assess files against your policy. We agree independence and reporting terms first. It does not replace a programme-wide independent AML audit.

Questions

Before you send the files.

Scope, pricing and the responsibilities your UAE team keeps.

Scope your UAE KYC work
What do your UAE KYC services cover?

Customer onboarding, CDD remediation, periodic reviews and agreed trigger-event reviews for funds, administrators, banks, brokerages and asset or wealth managers. We support UAE engagements, including Dubai, DIFC, Abu Dhabi and ADGM, under the entity’s approved AML policy and agreed regulatory scope.

Can you support both DIFC and ADGM firms?

Yes, subject to agreeing the entity, applicable requirements and engagement terms. DIFC firms use the relevant DFSA rules; ADGM firms use the relevant FSRA rules, alongside federal AML legislation. We configure the file work to your approved policy. A shared group policy does not remove the need to identify each entity’s obligations.

How does managed KYC support our UAE AML compliance work?

We complete agreed CDD checks under your approved policy and document the evidence, risk assessment and exceptions for your authorised team. This supports your customer due diligence and oversight of the outsourced work. Your firm retains compliance responsibility, customer acceptance, high-risk approvals and statutory reporting. The engagement is operational support, with your appointed MLRO and any legal reliance arrangements kept separate.

Can you review complex ownership and source of wealth?

Yes. We map the structure, assess ownership and control, and review the evidence required by your policy. A 25% ownership filter alone may miss control through other means. We record unresolved ownership links or unsupported explanations and route them to your team for a decision.

Do you handle goAML reporting or live transaction monitoring?

These managed KYC engagements cover the agreed customer file work. They do not include acting as your MLRO, submitting statutory goAML reports, executing asset freezes or operating live transaction monitoring. We agree urgent escalation routes before starting so a suspicious activity concern or sanctions hit reaches the responsible team promptly.

What does UAE KYC outsourcing cost, and where is the data held?

We quote per case after reviewing the population, ownership complexity, available evidence and scope. We confirm the price, delivery schedule and responsibility for missing documents in writing. Hosting location, access, cross-border transfers, retention and handover terms must be agreed before customer files are transferred; UAE-only hosting is not assumed.

Scope your UAE KYC work

Discuss your files

Get a quote for your UAE KYC work.

Bring the case count, regulator and target date. We’ll confirm the scope, price and delivery schedule in writing.

UAE KYC reviewsScope your backlog
Get a quote