United Kingdom KYC services · Financial services firms

Clear your UK KYC backlog.
Keep control of approvals.

We complete onboarding, CDD remediation and periodic reviews for UK financial services firms. Our compliance reviewers work under your AML policy and return documented files, with open questions flagged for your team’s decision.

Your AML policy · Qualified human review · Your team keeps approval

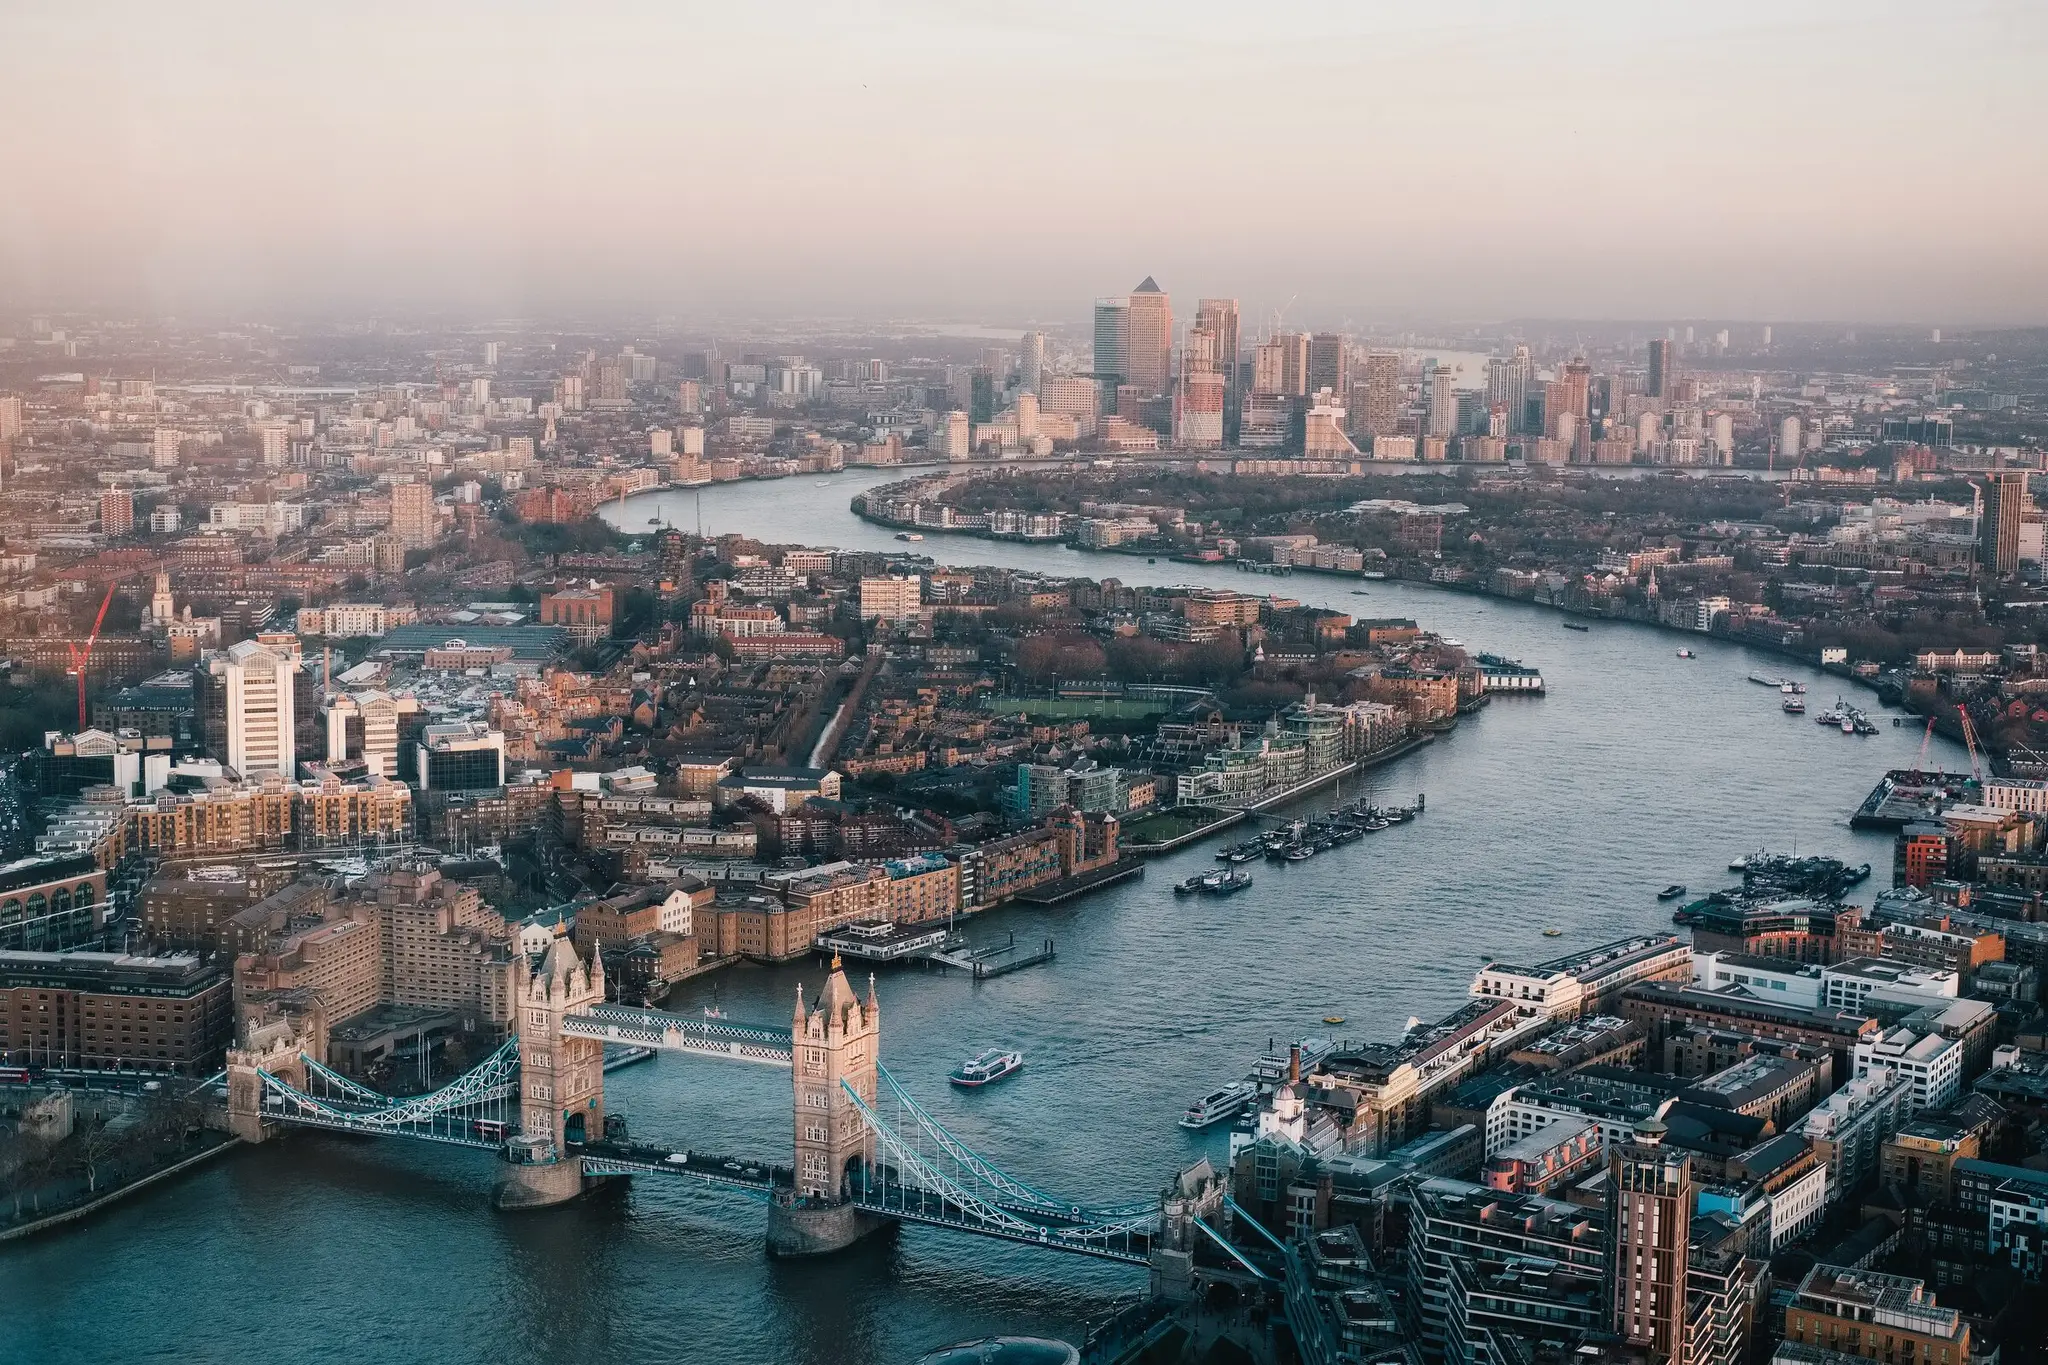
Tower Bridge and the River Thames winding through London, viewed from above

Managed KYC and AML remediation

Put a scope and a date on the backlog.

Use UK KYC outsourcing for a defined remediation project or recurring customer reviews. We agree the evidence standard, case priorities and escalation route before work begins.

01 · Customer onboarding

Move incomplete files towards approval.

We review identity evidence, trace beneficial ownership and control, and screen the relevant parties. Your approver receives the supporting documents, proposed risk assessment and questions that still need an answer.

02 · KYC remediation

Close the gaps in your existing book.

An old ownership chart or an unsupported source-of-funds explanation can keep a case open. We review the agreed population against your current policy, work the remediation and record missing evidence and escalations for your team.

03 · Periodic reviews

Work through overdue customer reviews.

We refresh CDD records and screening, document changes and reassess risk under your methodology. Reviews follow your risk-based timetable, with trigger-event work scoped separately when circumstances change.

Who we support in the UK

The review follows your customer relationship.

A fund investor, a corporate banking customer and an investment mandate need different evidence. We define the checks around the entity, activity and obligations in scope.

Funds and administrators

Investor onboarding, ownership checks and subscription-related reviews. We agree which entity holds the obligation and which checks an administrator performs on its behalf. A UK manager’s file does not automatically satisfy an offshore fund’s requirements.

Asset managers and investment firms

CDD for individual clients, corporate mandates and intermediary relationships. We document the customer, authorised representatives, ownership and purpose of the relationship against the policy for that business.

Banks and brokerages

Customer onboarding and remediation of retail or corporate files. We agree the population, risk priorities and evidence standard. Transaction monitoring, payment controls and suspicious activity reporting remain separately defined responsibilities.

UK Money Laundering Regulations · FCA oversight

Outsource the file work. Keep oversight of each case.

Regulation 39(7) allows CDD work through an outsourcing provider while the regulated firm remains liable for failures. FCA outsourcing requirements depend on the firm and the function being outsourced.

We agree the policy and evidence standard with your team, document the work and escalate exceptions. Your firm keeps customer acceptance, required senior-management approvals and suspicious activity reporting decisions.

Read UK AML guide

Read Regulation 39 alongside the FCA’s outsourcing guidance. Our UK AML compliance guide explains CDD, domestic PEPs, review triggers and the distinction between outsourcing and reliance.

What you receive

A file your approver can follow.

Each conclusion points to the evidence reviewed. Missing documents and unresolved risks stay visible at handover.

Included in the file

Identity and ownership evidence

An indexed file showing the customer, relevant parties and the evidence behind the beneficial ownership and control assessment.

Included in the file

Screening decisions and exceptions

Sanctions, PEP and adverse-media results with reviewer notes on potential matches. Domestic PEP treatment follows your policy and the applicable UK requirements.

Included in the file

Risk assessment and open questions

A proposed risk rating, source of funds and wealth evidence where required, and a list of missing documents or unresolved concerns.

Included in the file

Review record and handover

A record of the work performed, human review and exceptions for your authorised team. Approval and reporting decisions remain with your firm.

The process

Start with the case count and your deadline.

  1. 01 · Scope

    Define the population.

    Share the entity type, number of files and target date. We agree the policy, deliverables, data-handling terms and price before you send customer documents.

  2. 02 · Work & review

    We work each case.

    Agents organise documents and run the first pass. Qualified compliance reviewers check the evidence and reasoning, then escalate unresolved or higher-risk cases.

  3. 03 · Handover

    Your team decides.

    Receive reviewed files and an exception log. Your authorised team makes acceptance and reporting decisions. Recurring reviews follow the schedule you approve.

If your administrator already performs KYC, Shadow KYC file testing can provide a separately scoped review. We agree independence and reporting arrangements before starting; file testing does not replace a programme-wide AML audit.

Questions

Before you send the files.

Scope, pricing and the responsibilities your UK team keeps.

Scope your KYC backlog
What do your UK KYC services cover?

Managed customer and investor onboarding, CDD remediation, and periodic or trigger-event reviews for UK funds, administrators, asset managers, investment firms, banks and brokerages. We agree the legal entity, policy, case population and checks before starting. This is operational file work; wider AML controls need their own scope.

Can an FCA-regulated firm outsource KYC?

The Money Laundering Regulations permit CDD work through an agent or outsourcing provider while the firm remains liable for failures. Your firm must also assess the FCA outsourcing requirements applicable to its business. We agree oversight, access to records, escalation, data handling and exit arrangements before work starts.

How does AgentKYZ support our UK compliance team’s decisions?

We return human-reviewed CDD files with the evidence, risk assessment and unresolved concerns your team needs to assess the relationship. We escalate concerns through the agreed route to your MLRO and authorised approvers. Your firm retains compliance responsibility, customer acceptance, required senior-management approvals and suspicious activity reporting; those decisions and filings are outside this file-work engagement.

How do you handle UK politically exposed persons?

We review PEP matches and document the role, connection and relevant risk factors under your policy. UK domestic PEPs, their family members and known close associates have a lower-risk starting point than non-domestic PEPs. PEP status still requires proportionate enhanced due diligence; your team keeps the approval decision.

Can you check files already held by our fund administrator?

Yes. A separately scoped Shadow KYC review can test files against your approved policy and report exceptions. We agree independence and reporting arrangements before starting. File testing does not replace a programme-wide AML audit or a regulator-appointed skilled person review.

How much does UK KYC outsourcing cost?

We quote per case based on the population, ownership complexity, available evidence and review scope. Share the case count and target date. We confirm the price, delivery schedule, responsibility for missing documents and data-handling terms in writing before file transfer.

Scope your KYC backlog

Discuss your files

Get a quote for your UK KYC work.

Bring the case count, entity type and target date. We’ll confirm the scope, price and delivery schedule in writing.

UK KYC reviewsScope your backlog
Get a quote